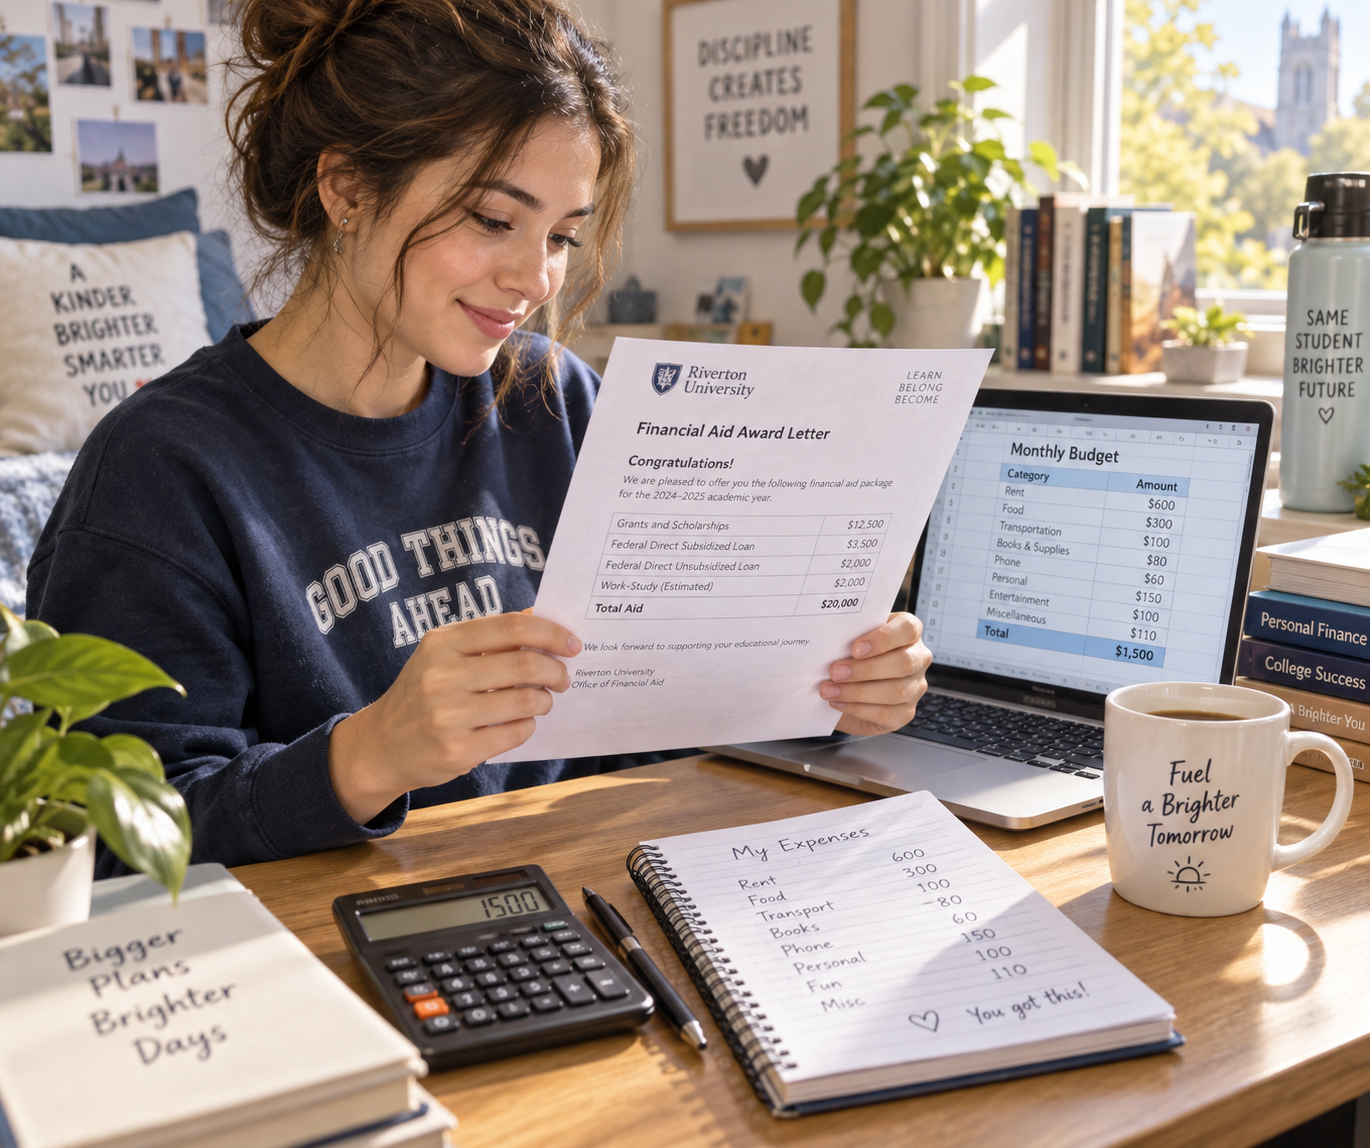
Student Finance 101: Budget, Borrow and Graduate Debt-Smart
Student finance is more than tuition. Learn how aid offers, federal loans, budgets and credit really work so you graduate with a degree, not a debt spiral.
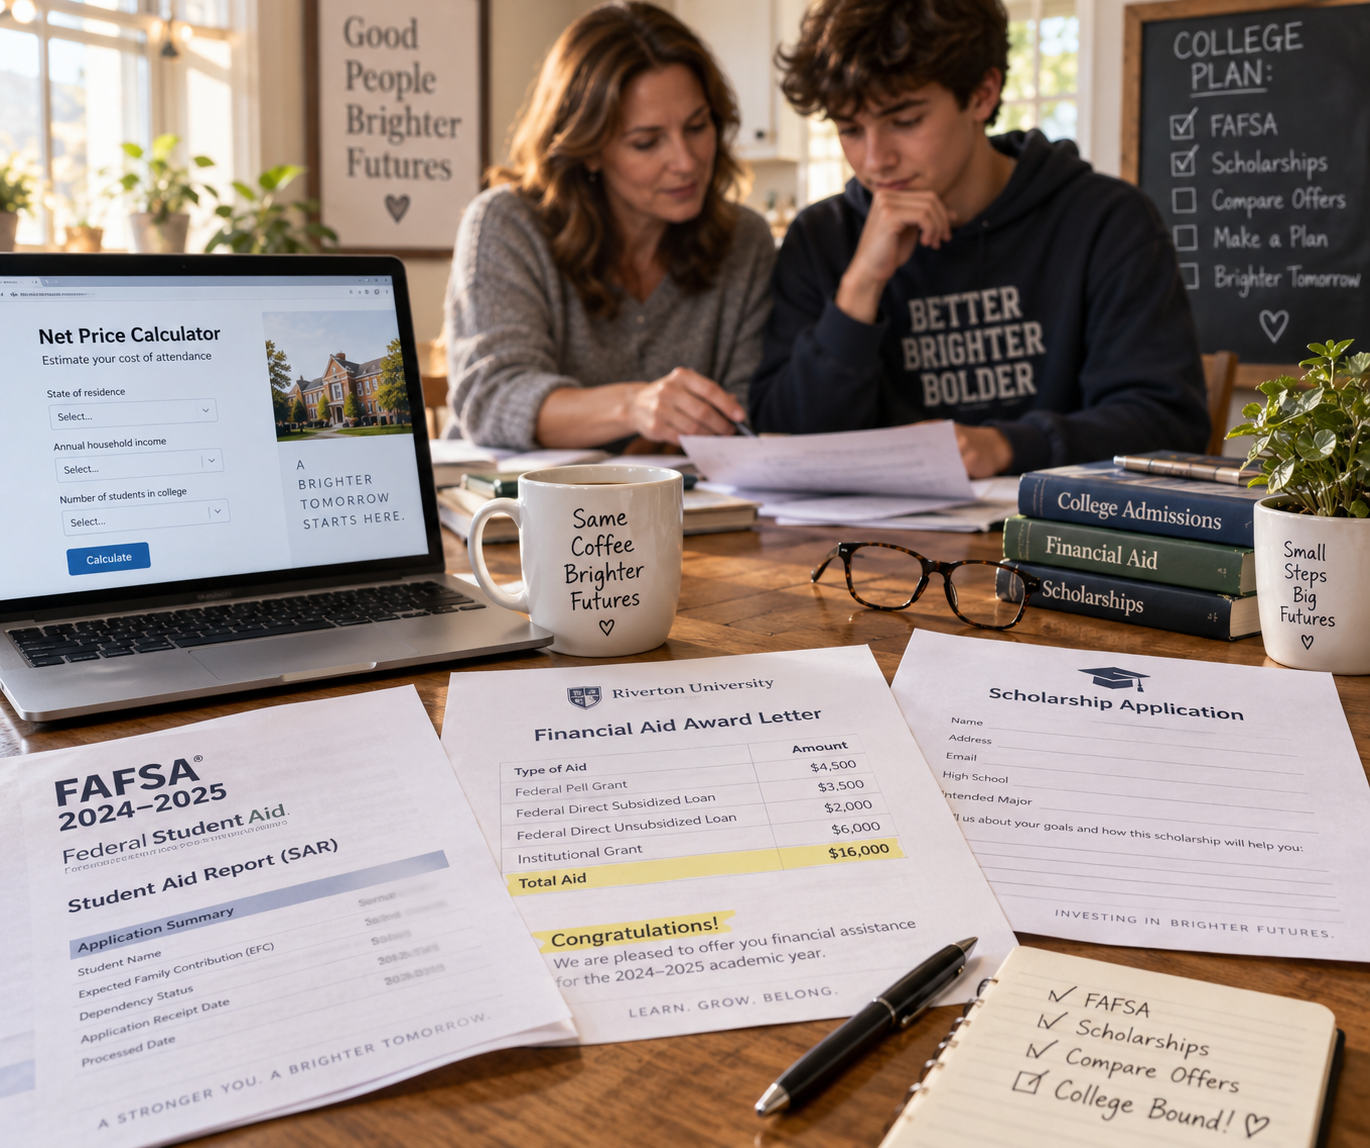
Every spring, millions of families open a financial aid award letter and try to decode it. The numbers look official, the vocabulary sounds legal, and the deadline is usually close. Student finance has its own language — cost of attendance, Student Aid Index, subsidized, disbursement, grace period — and learning that language is half the battle. The other half is refusing to treat borrowed money like income.
This guide walks through the pieces that actually move the needle: what college really costs, how to read an aid offer, which loans to take first, and how to build habits during school that keep your post-graduation options open.
The Only Number That Matters Is Cost of Attendance
Tuition is the headline, but it is rarely the bill. Colleges publish a cost of attendance (COA) that bundles tuition and fees, housing, food, books, transportation, personal expenses, and sometimes a loan fee allowance. Your total aid cannot exceed that figure.
When comparing schools, ignore the sticker price and look at net price — COA minus grants and scholarships you do not have to repay. Every college is required to post a net price calculator on its website. Ten minutes with that tool can reframe an entire decision.
How to Read an Aid Offer Without Getting Fooled
Award letters often present everything as one happy total. Sort it into three piles instead:
- Free money: grants and scholarships. Take all of it. This is the only category that never comes back to haunt you.
- Earned money: federal work-study. It shows up as wages, not a lump sum, so budget accordingly.
- Borrowed money: federal student loans and any private loans. Every dollar here carries interest and a future payment.
A common mistake is counting a loan as an award. It is not an award. It is a debt you are agreeing to before you have a paycheck.
Federal vs. Private Loans
Federal loans come with fixed interest rates set once a year, access to income-driven repayment, forgiveness programs for public service, deferment if you return to school, and discharge in cases of death or total disability. Private loans are credit-based, may carry variable rates, and offer far fewer safety nets. They often require a cosigner who is fully on the hook.
The order of operations is simple: fill out the FAFSA every single year, exhaust federal aid, then consider private borrowing only for a genuine gap. The FAFSA is free — never pay a service to complete it.
Subsidized vs. Unsubsidized in Plain English
Subsidized loans are need-based, and the government pays the interest while you are enrolled at least half-time and during your six-month grace period. Unsubsidized loans are available to almost everyone, but interest starts accruing the day the money is disbursed. If you can pay even the interest on unsubsidized loans while in school, you will shave real money off your balance.
Build a Budget That Survives the Semester
A budget built in September often dies by October. Start by tracking one month of actual spending before you set limits. Then divide your monthly money into four buckets: fixed costs (rent, phone, insurance), variable needs (food, transport, supplies), flexible wants (streaming, going out), and a small emergency fund.
Watch the quiet leaks — subscription stacking, delivery fees, and daily coffee runs. They rarely feel like decisions, which is exactly why they add up to hundreds per semester.
The Refund Check Trap
When your aid exceeds your direct charges, the school sends you a refund. It feels like a windfall. It usually is not. If you borrowed the money, that refund is debt in cash form. Treat it as a restricted education account: textbooks, a laptop, transportation, rent. Students who spend refunds on spring break are simply paying for that trip with interest for the next decade.
Work Wisely, Not Just Hard
Work-study jobs are based on financial need and tend to be flexible around class schedules — library desks, lab assistants, campus offices. Off-campus jobs can pay more but eat commuting time. For most full-time students, staying under roughly 15 to 20 hours a week protects grades, which protects scholarships, which is worth more than the extra shifts.
Protect Your Credit From Day One
Your credit score will decide your car loan rate and whether an apartment lease gets approved. Build it deliberately: pay on time every time, keep credit card balances under about 30 percent of your limit, and avoid closing your oldest account. A student card used for small recurring purchases and paid in full monthly does more for your file than any financial literacy seminar.
Understand Repayment Before You Graduate
Your grace period is typically six months after you drop below half-time enrollment. Use it. Log into the federal student aid portal, find out who services your loans, and choose a repayment plan rather than defaulting into the standard one by accident.
Income-driven repayment plans cap monthly payments at a percentage of discretionary income and offer forgiveness after a set number of years. Rules and available plans have shifted in recent years, so verify current options directly with your servicer before making decisions. Never ignore a delinquency notice — default can garnish wages and tax refunds and wreck your credit for years.
Five Habits That Compound
- Reapply for aid and scholarships every year; most students stop too early.
- Borrow only what the semester requires, not the maximum offered.
- Pay unsubsidized interest while enrolled if any cash allows it.
- Track one number: total debt versus expected first-year salary.
- Ask the financial aid office directly — they can adjust offers when circumstances change.
Student finance rewards the boring playbook: free money first, earned money second, borrowed money last, and none of it spent casually. Graduate with a degree and a plan, and the loans become a manageable line item instead of a decade-long weight.