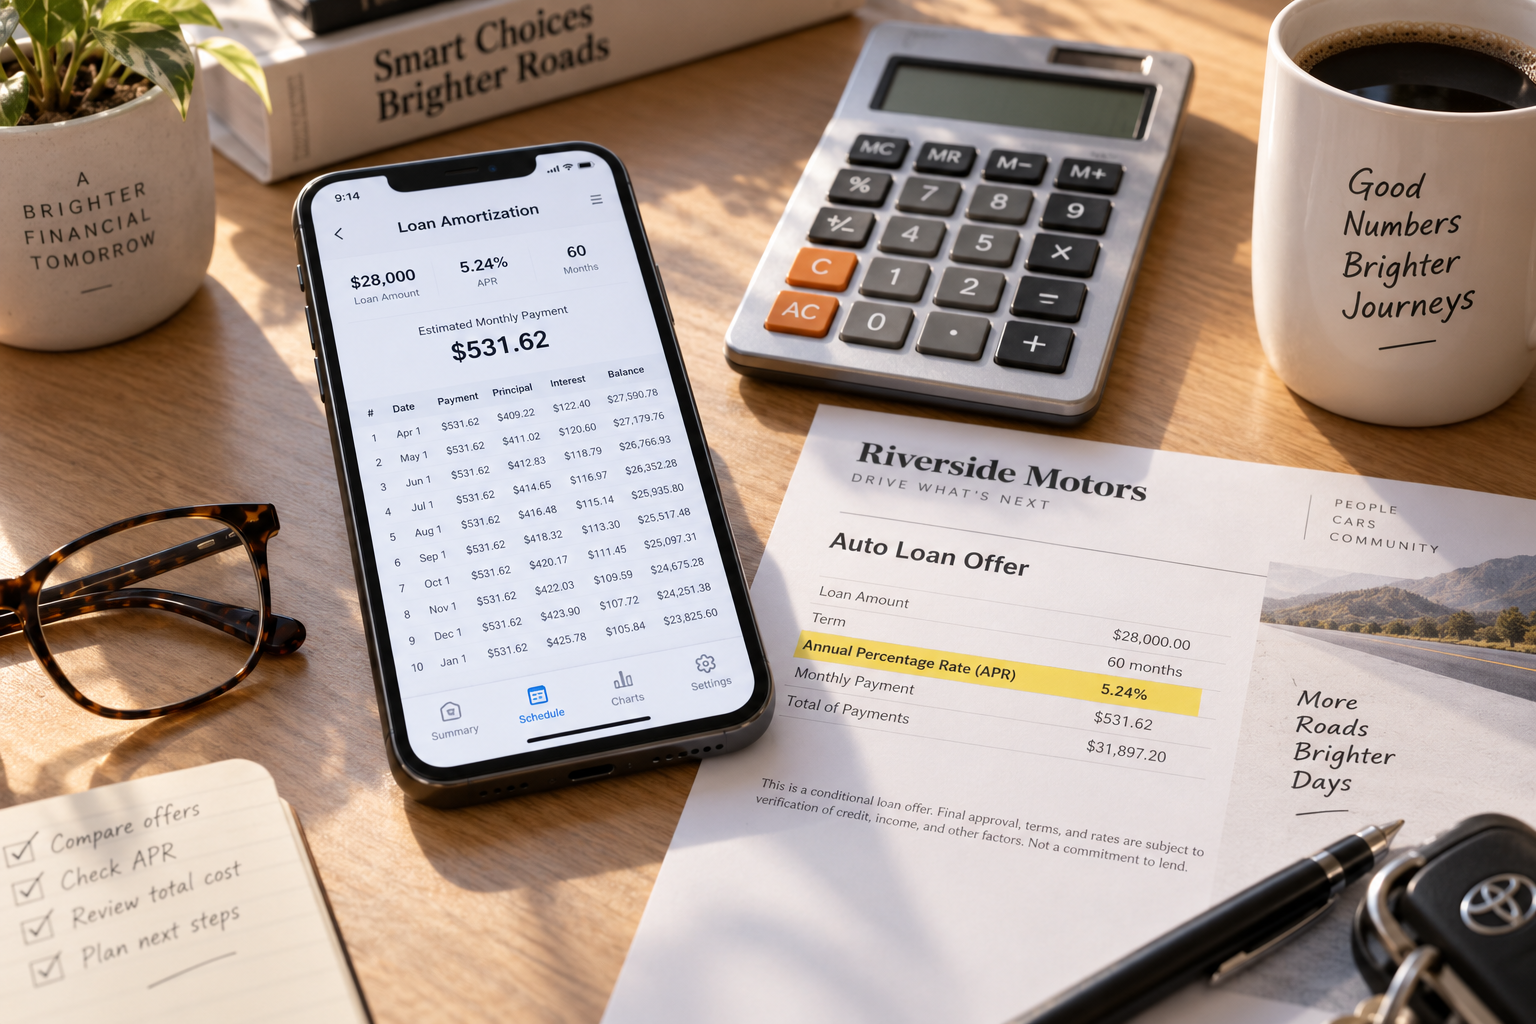
Loan Calculator: The Math That Decides What You Pay
A loan calculator is only as honest as the numbers you feed it. Here's how to read the monthly payment, the APR and the real total cost of borrowing.
Why the Monthly Payment Is Only Half the Story
Type a few numbers into a loan calculator and it hands back a figure that feels like an answer. It is not. The monthly payment is a snapshot of one month; the loan itself is a decade-long relationship between you and a lender, and the calculator only knows what you tell it. Feed it a rate that excludes fees, a term you never intend to keep, or an amount that quietly includes taxes and dealer add-ons, and the number on screen is fiction dressed as arithmetic.
That doesn't make loan calculators useless. It makes them instruments. Used well, they are the fastest way to see how a 60-month term compares with a 72-month one, or what an extra $50 a month does to the total interest you hand over. Used badly, they become a machine for justifying a purchase you can't quite afford.
How a Loan Calculator Actually Works
The formula behind the button
Most amortized loans — auto, personal, and student — use the same equation:
M = P x [ i(1 + i)^n ] / [ (1 + i)^n - 1 ]
Here M is the monthly payment, P is the principal, i is the monthly interest rate (the annual rate divided by 12), and n is the number of monthly payments. The formula spreads principal and interest so the loan reaches zero exactly on schedule. Early payments are mostly interest; late payments are mostly principal. That front-loading is why paying extra in year one saves far more than paying the same amount in year five.
What the inputs really mean
- Principal: the amount actually financed — not the sticker price, but what remains after down payment and trade-in, plus taxes and fees.
- Rate: the annual cost of borrowing the principal. It is not the APR.
- Term: how many months you'll pay. Longer terms shrink payments and inflate total interest.
Where Calculators Get Quiet
Every honest calculator has blind spots. Knowing them is most of the work.
- Origination fees. Many personal loans deduct roughly 1% to 8% before the money reaches you. Borrow $10,000 with a 5% fee and you receive $9,500 while repaying $10,000 plus interest. The APR reflects this; the quoted rate does not.
- Variable rates. If the rate can reset, your payment can rise. A calculator assuming a fixed 9% for eight years is describing a loan you may not actually have.
- Capitalized interest. On some student loans, unpaid interest is added to principal at certain points, and you then pay interest on that interest.
- Insurance and add-ons. GAP coverage, extended warranties, and credit insurance are frequently rolled into auto loans, raising both the principal and the interest charged on it.
- Prepayment penalties. Rare but real. If your plan is to pay off early, confirm there's no charge for doing so.
Auto, Personal, Student: Same Tool, Different Traps
Auto loans
Dealers quote a payment, not a price. That is the oldest trick in the showroom. Negotiate the out-the-door price first, arrange financing second, then use a calculator to model the real loan amount — including sales tax, registration, and any negative equity carried over from a trade-in. A six- or seven-year term can make an expensive vehicle feel affordable while keeping you underwater for years.
Personal loans
These are usually unsecured and fixed-rate, which makes them calculator-friendly. Compare offers by APR rather than interest rate, and check whether the fee is baked into the rate or deducted upfront. A no-fee loan at 14% can cost more than a 12% loan with a 3% origination fee — or less. Only the math settles it.
Student loans
Federal loans come with fixed rates set annually, income-driven repayment options, and forgiveness programs that a basic calculator cannot model. Private loans behave more like personal loans but often lack the same protections. If you're weighing the two, run the numbers twice: once for the standard ten-year plan and once for the income-driven scenario you would realistically choose.
Three Numbers to Compare Every Offer
- Monthly payment: what fits your budget now.
- APR: the true annual cost including most fees — the single best comparison figure.
- Total interest paid: the number that reveals whether the cheaper monthly payment is actually cheaper.
If a lender won't give you all three in writing, that silence is data too.
How to Run a Smarter Scenario
Once you have the basics, use the calculator to stress-test the loan rather than admire it.
- Model one term shorter than you planned. The payment rises modestly; the interest often falls by thousands.
- Add $50 or $100 to the monthly payment and watch how many months vanish from the schedule.
- Compare a 15% rate against a 9% rate on the same principal — the gap is usually larger than people expect.
- Assume a biweekly schedule: 26 half-payments equal 13 full payments a year, which typically trims years off the term.
The Bottom Line
A loan calculator doesn't tell you what to borrow. It tells you the price of the choice you're about to make — interest, fees, and time included. Enter honest numbers, read the APR, check the total interest, and treat any payment that only works on an 84-month term as a warning rather than a solution.